 Diaspora
Can you buy land in instalments in Cameroon?
Buying land in instalments in Cameroon? Learn what to agree before paying, when title transfers, and how to protect deposits and diaspora payments.
28 October 2026 · 8 min read · VERA237 Editorial
Research checked: 28 October 2026. This guide provides general information, not advice on a particular contract.
Quick answer
Yes, some sellers in Cameroon offer payment by instalments. But an affordable payment schedule is not the same as a protected purchase. Published seller offers confirm that staged payments are available under individually agreed terms; they do not establish a universal deposit, repayment period or buyer-protection guarantee. (fonciercameroun.com)
Before committing, have a Cameroonian notary review the proposed arrangement and explain what rights you receive before the final payment. Ask a lawyer to assess cancellation, refund and enforcement clauses where necessary.
For a diaspora buyer, the essential question is not simply, “Can I afford the monthly amount?” It is: “What protects the money I have already paid if the transaction stops?”
This guide concentrates on that payment risk—not the full land-verification process.
What does buying land in instalments actually mean?
In the seller arrangements examined for this article, the buyer pays the purchase price in several agreed portions rather than obtaining a separate bank loan. One seller's published explanation expressly makes the timetable dependent on the buyer's circumstances and calls for written terms covering instalments and late payment. That is the seller's offer, not a rule applying to every transaction. (sciminiature.com)
Ask the seller to identify exactly what is being proposed:
- A reservation while you arrange financing?
- A preliminary commitment followed by a later sale?
- A notarised sale with some purchase money still outstanding?
- Payments towards a plot that has not yet been individually identified?
Do not accept these descriptions as interchangeable. Ask the notary to explain the legal effect of the actual document—not just its heading.
If you are comparing seller instalments with borrowing, Crédit Foncier du Cameroun's published lending guide includes building-land purchases and addresses Cameroonian salaried workers, including the diaspora. Obtain a current eligibility assessment and quotation directly; a seller's payment plan is not evidence of loan approval. (creditfoncier.cm)
When will the land title be transferred?
Do not assume that paying the first instalment, or even the final one, automatically completes registration. MINDCAF's published procedure for a whole-property sale distinguishes the notarised deed, registration of that deed, and mutation of the title in the land register. A collection of payment receipts is not that completed process. (mindcaf.gov.cm)
Put this question to the notary before signing:
At what stage will the sale deed be executed, when will the transfer application be submitted, and what evidence will I receive at each stage?
Then request written answers to three further questions:
- Who remains the registered owner while instalments are outstanding?
- What legally effective protection can be put in place during that period?
- What happens if the seller dies, becomes insolvent, refuses to cooperate or attempts another transaction involving the land?
Do not assume that a contractual promise not to resell provides the same protection as an appropriate registered right. Ask the notary or lawyer to explain the available safeguards and their limits for your specific arrangement.
Where the proposed plot forms part of a larger titled property, ask for the precise parcel identification and the procedure needed to create your title. MINDCAF's manual treats subdivision transfers, commonly called morcellement, separately from whole-title mutation. (mindcaf.gov.cm)
Involve the notary before the first substantial payment
Avoid agreeing to a payment timetable first and leaving the legal structure until the balance is paid.
Crédit Foncier's practical guide advises that a promise of sale should be formalised by a notary after the usual checks. Although this guidance appears in a lending document, it provides a useful safeguard to discuss for a seller-instalment purchase too. (creditfoncier.cm)
For the initial consultation, assemble:
- The seller's identity and any document authorising someone else to act.
- The title reference, available title copy and parcel plan.
- The proposed contract and payment schedule.
- Advertisements, messages and any promised discounts.
- Details of the proposed payment recipient.
- Any receipts for money already paid.
Ask the notary to obtain or verify current registry information. MINDCAF's published whole-property sale procedure begins with updating information about the seller's property through a certificate of ownership, or certificat de propriété. (mindcaf.gov.cm)
The payment agreement: questions it should answer
The following is a VERA237 contract-review worksheet, not a statutory contract template. Take it to your notary or lawyer and ask which protections can be included and enforced.
| Issue | Question to resolve in writing |
|---|---|
| Exact property | Which title, parcel, area and plan does every payment relate to? |
| Total price | What is the agreed purchase price in FCFA, and can it change? |
| Initial payment | Is it part of the price, a reservation charge or another fee? |
| Due dates | What amount is due, when, and what counts as payment received? |
| Seller obligations | Which documents or procedural steps must the seller complete? |
| Payment custody | Who receives or holds funds, and under what release conditions? |
| Buyer delay | What notice, opportunity to remedy, charges or cancellation terms apply? |
| Seller failure | When can the buyer seek cancellation or repayment, and by what procedure? |
| Completion | When are the deed, filing and title-transfer steps expected? |
| Disputes | How are notices served and disputes handled? |
Make refund terms specific
Ask for an explanation of every amount described as non-refundable. Request a written calculation of the possible outcome if you withdraw, miss an instalment, or discover that the seller cannot complete.
Also ask who owes the refund: the registered owner, an agency or a development company. Have your lawyer assess whether the wording gives you a realistic remedy against the correct party.
Ask about holding funds—not just sending them
Ask whether a suitable notarial holding arrangement is available for the transaction, what account would be used, and what written instructions govern release and return.
Do not treat the word escrow in an advertisement as proof of protection. Request the actual arrangement, independently confirm the recipient and ask your adviser to explain what happens if the transaction fails.
Budget beyond the advertised instalment
Request an itemised FCFA budget separating:
- Purchase price and any deferred-payment premium.
- Notarial charges and legal review.
- Registry checks and cadastral work.
- Applicable registration duties, land charges and stamps.
- Transfer fees, currency-conversion costs and any late-payment charges.
For a limited official reference, MINDCAF's published FAQ lists 5,000 FCFA per title for a property statement, or relevé immobilier. This is not the total cost of verification or transfer. Confirm the exact service, current charge and payment instructions with the competent registry. (mindcaf.gov.cm)
No nationwide seller-instalment deposit or standard repayment period was established by the sources reviewed. Request the seller's complete written quotation rather than applying another company's advertised terms to your purchase.
For buyers earning dollars or pounds, build your personal budget around the amount that must arrive in FCFA. Ask how transfer charges and payment delays will be treated. Leave room for legal and administrative expenses rather than committing every available saving to the deposit.
Scam warnings: cheap monthly payments do not verify a plot
There is documented reason to check the underlying paperwork independently. In an announcement published on 12 December 2025, MINDCAF reported a decision dated 21 November 2025 provisionally suspending cadastral personnel over alleged misconduct including land-map falsification, abusive retention of files and overbilling. That announcement is not proof of a criminal conviction or evidence against any particular seller. (mindcaf.gov.cm)
Our practical conclusion: do not let a manageable instalment distract you from unresolved document problems.
Treat these as reasons to seek clarification—not automatic proof of fraud:
- The seller refuses review before a reservation payment.
- The agreement cannot identify the exact plot.
- The receiving account changes without a documented explanation.
- Only your payment deadlines are specified; the seller has no completion obligations.
- Promised refund conditions disappear from the written contract.
- An intermediary says official checks are unnecessary because they know someone inside the administration.
Does digitalisation make a screenshot sufficient?
No such conclusion follows from the current announcement. On 16 October 2026, MINDCAF reported a digitalisation planning workshop held the previous day. Its preliminary roadmap places groundwork in 2027 and deployment in 2028. This describes a programme being developed, not proof that every private plot can already be conclusively verified through an online screenshot. Confirm the available verification channel with the competent registry. (mindcaf.gov.cm)
A diaspora example: affordable payments, unanswered obligations
Illustrative scenario—not a reported case.
A buyer in Canada is offered instalments on a plot near Yaoundé. The proposed agreement lists every payment date but says only that the title will follow after full payment. It does not identify who must prepare the transfer file, provide a completion deadline or explain refunds if the seller cannot complete.
Rather than treating the manageable payments as sufficient reassurance, the buyer sends the draft to a notary and asks for clarification of the parcel, legal structure and completion responsibilities.
Use the same test for your own proposal: can you describe the seller's next obligation as precisely as your next payment?
Your pre-payment checklist
Use this checklist as a discussion tool—not a substitute for professional clearance.
- The exact plot is identified in the proposed agreement.
- The seller's identity and authority have been independently checked.
- The notary has explained the current registry position.
- I understand when the deed and title-transfer steps will occur.
- The complete price and additional costs are stated in FCFA.
- Payment recipients and any holding arrangements are independently confirmed.
- Buyer-delay and seller-failure provisions have both been reviewed.
- Refund conditions, deductions and procedures are explicit.
- Each payment will have an identifiable reference and acknowledgment.
- I have a plan for monitoring the transaction from abroad.
If you have already started paying and discover a problem, preserve the agreement, messages and receipts. Seek legal advice promptly before missing a contractual deadline, signing a replacement agreement or sending additional money to resolve an unexplained issue.
What to do next
Request the draft agreement and complete payment schedule before making a decision. Ask a notary to explain the transaction structure and a lawyer to review disputed or unclear cancellation provisions.
If you approach VERA237 about verification services, request a written scope: which checks are included, who performs them, what evidence you receive and what remains outside the service. Verification support should complement—not replace—the notary, registry and other qualified professionals.
Key takeaways
- Judge an instalment offer by its protections, not just its affordability.
- Ask when ownership formalities occur and what protects earlier payments.
- Require clear obligations for the seller as well as the buyer.
- Resolve refund, default and payment-custody questions before committing.
- Do not purchase, sign or transfer funds solely on the basis of this article.
Frequently asked questions
Can I pay for land monthly in Cameroon?
Some sellers offer instalments, but monthly payments are not a universal entitlement. Obtain a written proposal specifying the price, due dates, late-payment terms and completion arrangements, then have it reviewed independently. Published seller offers confirm that schedules are individually agreed. ([sciminiature.com](https://sciminiature.com/paiement-echelonne/))
How much deposit is required for land in Cameroon?
The sources reviewed did not establish a nationwide deposit for seller-instalment purchases. Ask for the proposed amount in FCFA, its legal purpose, whether it counts towards the price and its refund conditions. Do not mistake one seller's advertised terms for a national requirement.
Does the final instalment automatically put the land title in my name?
Do not assume so. MINDCAF's published procedure distinguishes the notarised sale, registration of the deed and mutation in the land register. Ask your notary for evidence that the required transfer steps have been completed. ([mindcaf.gov.cm](https://www.mindcaf.gov.cm/media/filer_public/6a/cb/6acb60c5-4852-48a4-be8a-d806aca2c0a2/matrice_des_procedures.pdf))
What happens if I miss a land instalment?
The answer depends on the agreement and applicable law. Before signing, ask a lawyer to explain notice requirements, any opportunity to remedy the delay, charges, cancellation provisions and the treatment of previous payments. If a payment is already at risk, seek advice before the deadline.
Can I get my instalments back if the seller cannot complete?
Do not assume an automatic or immediate refund. Ask a lawyer to assess your agreement, the reason completion failed, the evidence of payment and the remedies available. Before committing, request explicit repayment obligations and advice on how they could be enforced.
Should a notary review an instalment purchase before I pay?
Yes—request review before committing funds, rather than waiting until the final instalment. Crédit Foncier du Cameroun's published guide advises that a promise of sale should be formalised by a notary after the usual checks. Ask how that safeguard should be applied to your transaction. ([creditfoncier.cm](https://creditfoncier.cm/fr/component/phocadownload/category/5-le-guide-de-l-emprunteur.html?download=3%3Aguide-pret-foncier-classique))
Relevant on VERA237
Useful next steps for this topic
Explore live listings and professionals whose work matches what you are reading.
Properties you may want to see
Browse all properties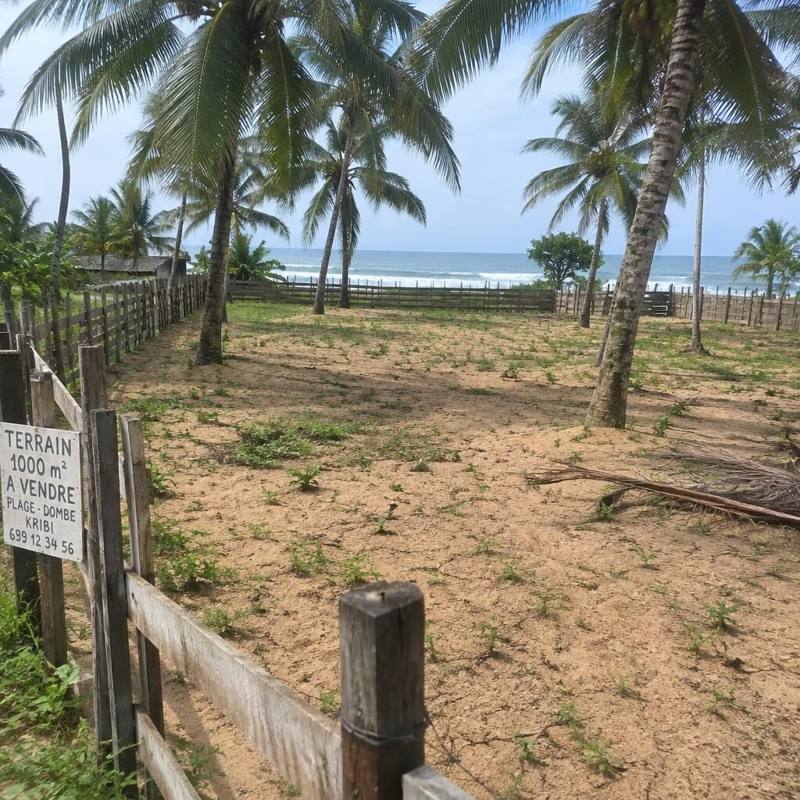
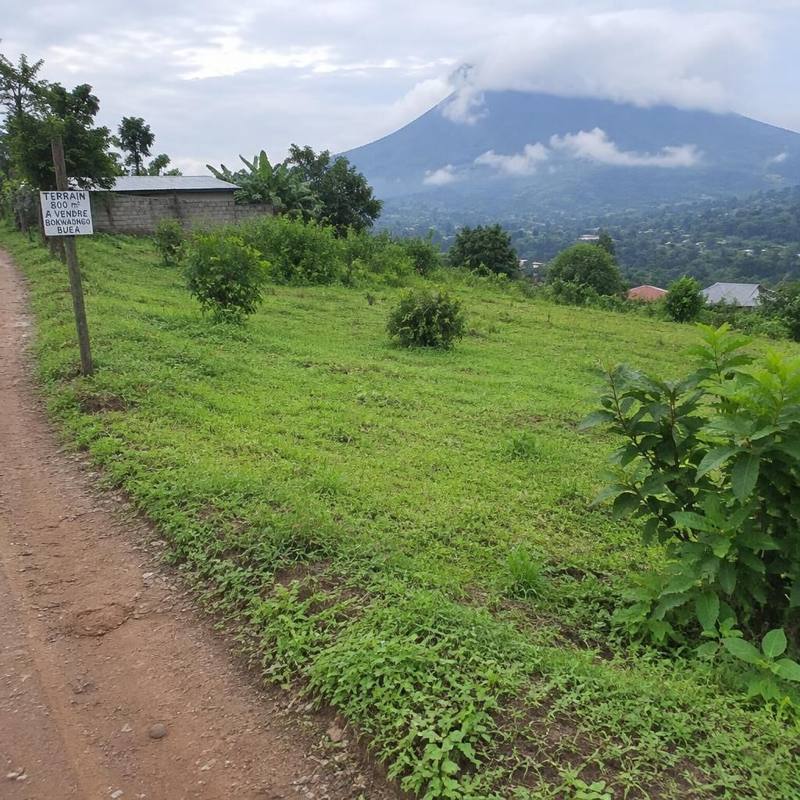
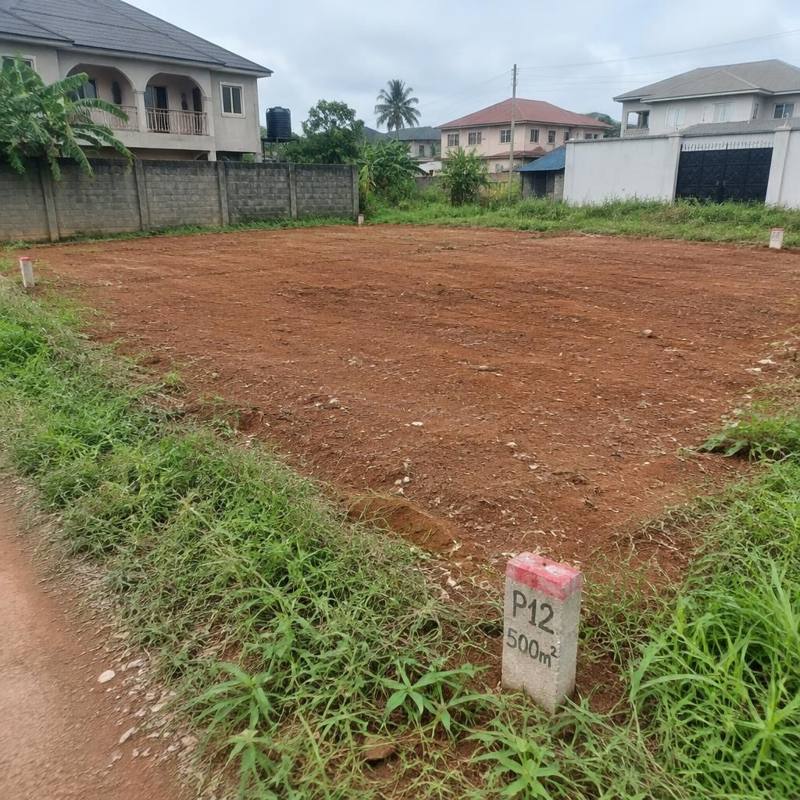
General information only, not legal advice. Always confirm current rules with a notary, lawyer or the land registry before paying. Written with AI assistance and published by VERA237.